10 Basic Accounting Principles Your Outsourced Accountant Should Know
In Australia, accounting isn’t just about balancing books but more about understanding the rules behind local law.
Yet, many offshore firms rely on IFRS or US GAAP, which don’t meet Australian compliance requirements.
This blog explores 10 basic accounting principles your outsourced accountant must know to support your business correctly and compliantly.
What Basic Accounting Principles Should Your Outsourced Accountant Know?
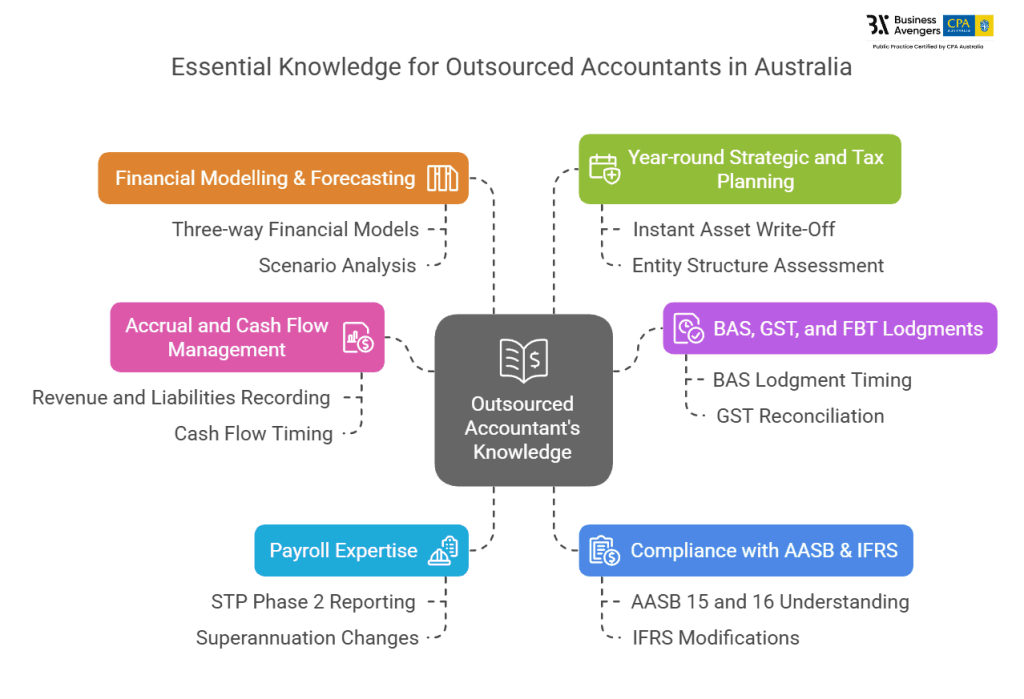
A dedicated outsourced accountant must know more than just how to set your company ledger and financial statements. They must demonstrate a practical grasp of Australia’s regulatory accounting standards to help your business stay compliant and financially healthy.
1. Accrual and Cash Flow Management Check
Accrual accounting is mandatory for financial reporting under AASB 101 and 15, which define when revenue and liabilities should be recorded. Your outsourced accountant must know the difference between cash and accrual accounting.
However, financial reporting under AASB standards often requires accrual methods.
Offshore accountants unfamiliar with AASB-modified IFRS may misreport performance-based income or long-term contracts.
3. Payroll Expertise with STP Phase 2 and Superannuation Changes
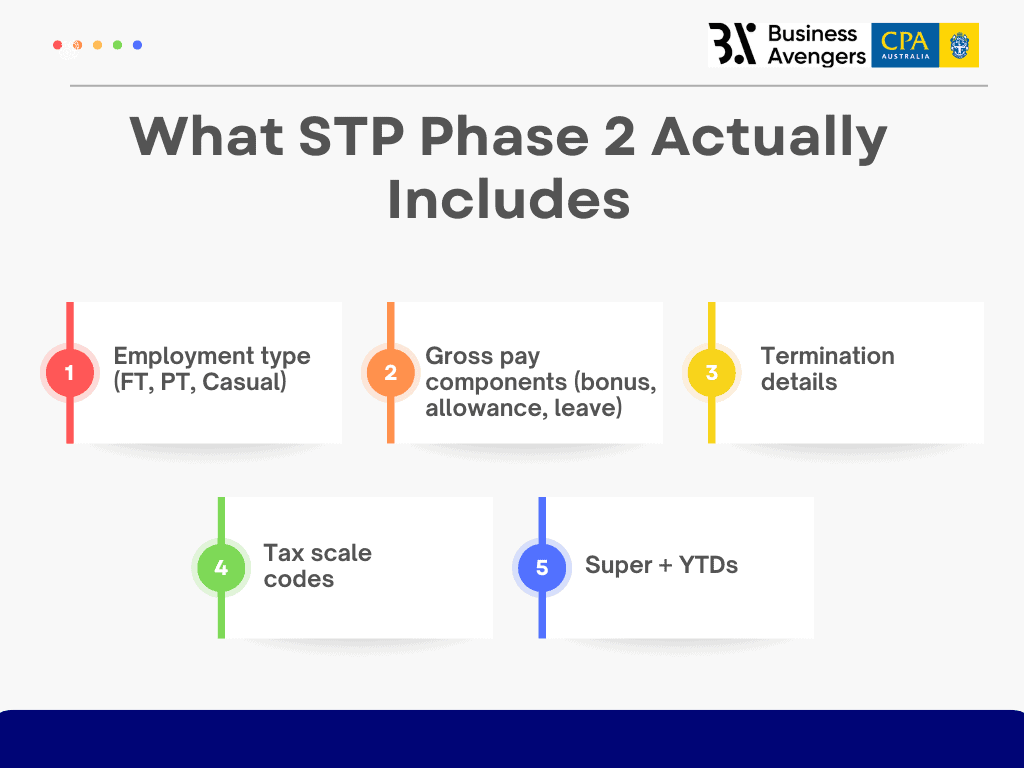
Australian payroll management system has witnessed two significant developments, which include the expansion of Single Touch Payroll (STP) Phase 2 and the scheduled increase in the Superannuation Guarantee (SG) rate.
Your accountant must know how to break down gross income into specific components, like allowances, overtime, bonuses, and commissions.
Understanding these reporting requirements is key to applying basic accounting principles to real-time payroll compliance. Payroll reporting now encompasses employment basis (e.g.g., Medicare exemptions, study loans), and discontinuing details upon termination (with reasons).
Your outsourced accountant must also include detailed reporting of termination payments, including redundancy payouts and unused leave. Moreover, as part of the government's plan to enhance retirement savings, the Superannuation Guarantee (SG) rate has been increased to 11.5% effective 1 July 2024, continuing its gradual rise toward 12% in 2025. This increment necessitates:
If your business fails to comply with these requirements, it can lead to penalties and increased scrutiny from regulatory bodies.
- Anticipating the financial impact of increased superannuation obligations on business cash flows and making necessary budgetary provisions.Employers must ensure super payments match the new rate.
- Leveraging accounting software like MYOB, Xero, and Employment Hero (enabled with STO Phase 2) to automate superannuation calculations and payments, thereby reducing errors and ensuring timely compliance.
- Accountants must recalculate employee cost forecasts and budgets to reflect the SG increase. Missed super payments, even if unintentional, can lead to a Superannuation Guarantee Charge (SGC) and damaged employee trust.
4. Understanding Real Compliance: Adherence to AASB & IFRS
Accurate financial reporting is a foundational part of basic accounting principles and not just a box to tick for your Australian business. If you want to scale, win tenders, or attract investors, your business finances must comply with AASB standards (incorporating IFRS with modifications).
Your outsourced accountant must know the differences and implications of AASB 15 and AASB 16, particularly for industries like construction, SaaS, retail, and multi-entity companies. AASB 15 governs how businesses recognise revenue when performance obligations are met. It is typically crucial for companies with:
What must your accountant do?
Identify contract deliverables, allocate price, and recognise revenue as control transfers. Moreover, in AASB 16, businesses must recognise right-of-use assets and lease liabilities on the balance sheet. This impacts EBITDA, loan covenants, and lease-heavy businesses.
An offshore accounting team applying US GAAP or older AASB 117 rules may understate liabilities, creating non-compliant financial statements. Beyond measuring technical accuracy, outsourced accountants must operate under strict ethical guidelines suggested by the APESB (Accounting Professional & Ethical Standards Board).
Accounting professionals must follow the APES 110 Code of Ethics for Professional Accountants (endorsed by CPA Australia), which states that an accountant must adhere to principles like maintaining integrity, objectivity, professional competence, due care, confidentiality, and applicable professional behaviour.
- Long-term contracts
- Subscription billing
- Milestone-based project work
5. Financial Modelling & Forecasting Proficiency
The true value lies in partnering with professionals who can deliver forward-looking insights. One of the most critical capabilities your outsourced accountant should bring is building and maintaining a three-way financial model, which connects the Profit & Loss (P&L), Balance Sheet, and Cash Flow Statement into a cohesive picture.
A 3-way model synchronises P&L, balance sheet, and cash flow to reveal true financial health. For example, a boost in sales revenue (P&L) should increase receivables (Balance Sheet) and later convert them into incoming cash (Cash Flow). Modern businesses also need scenario and sensitivity analysis so that their financial models do not remain static.
What happens if your sales fall by 15% or wages rise due to inflation? These scenarios help you plan cash reserves and identify when you may need to raise capital or assess debt capacity. With rising operating costs across many industries, sensitivity analysis is now a standard CFO-level expectation, even for small businesses.
Identify contract deliverables, allocate price, and recognise revenue as control transfers. Incorrect revenue recognition affects reports, valuations and more. Moreover, in AASB 16, businesses must recognise right-of-use assets and lease liabilities on the balance sheet. This impacts EBITDA, loan covenants, and lease-heavy businesses.
7. Acknowledging Industry-specific Accounting
Your outsourced accountant must apply basic accounting principles through the lens of your industry.
Hospitality
Your outsourced accountant must integrate POS and roster systems (like Kounta) with Xero/MYOB, review payroll against award requirements, and automate STP reporting.
E-commerce
Construction
Pro tip: Use job-costing modules in software (like simPro, WorkflowMax), audit subcontractor statuses annually, and apply stage-of-completion revenue recognition with supporting documentation.
- Shift-based rosters and awards: Penalty rates, overtime, and award compliance must be tracked via integrated payroll systems (e.g., Deputy, Tanda with Xero or MYOB).
- High staff turnover: Constant onboarding/offboarding increases STP Phase 2 reporting obligations (e.g., accurate cessation reasons, TFN declarations, super choice forms).
- Reconciling across platforms: Selling on Shopify, Amazon, and eBay means income arrives through various gateways. Sales must be reconciled with payment delays, merchant fees, and refunds, often manually if tools are not integrated.
- Job costing and WIP tracking: Costs must be accurately assigned to individual jobs. Underestimating job costs leads to margin erosion. Work-in-progress (WIP) should be reported on the balance sheet when jobs are incomplete.
8. Compliance with Australian Data Retention & Privacy Laws
Australian data privacy and retention compliance is a basic accounting principle that offshore or cloud-based accounting and bookkeeping teams often overlook. Businesses remain legally accountable for how financial data is stored, accessed, and protected, regardless of who manages it.
That’s why your outsourced accountant must align with the Australian Privacy Principles (APPs) and legal data retention periods, primarily if you use cloud-based platforms.
Australia’s Privacy Act 1988 outlines 13 Australian Privacy Principles (APPs), which apply to any organisation that collects and handles personal or sensitive information. Most accounting and payroll-related tasks fall under this.
Note: If your outsourced accounting service provider is storing data in offshore servers (e.g., US or India), it must comply with APP 8, i.e., cross-border disclosure obligations.
You must ask your outsourced accountant about the effective management of financial data. These include:
If they hesitate on any of these, it’s a red flag!
- This retention period starts from the date the record is prepared or the transaction is completed, whichever is later.
- For companies, under ASIC guidelines, some financial records (like annual financial statements) must be retained for 7 years.
- Use cloud providers hosted in Australia or ones with substantial privacy compliance (e.g., AWS Sydney region, Microsoft Azure AU Central).
- Have access controls in place (e.g., MFA, IP whitelisting).
- Conduct routine data backups and store them in encrypted formats.
- Offer client data retrieval on request within 7 days (to meet record access needs during audits).
- Have an incident response plan or team in case of cyberattacks.
9. ERP Integration Support & Automation Readiness
Using more comprehensive software solutions other than Xero and MYOB offers better accounting support. Integrating with ERPs (Enterprise Resource Planning) such as NetSuite, Zoho, SAP, and Microsoft Dynamics 365 helps you automate accounting tasks such as invoicing, reporting, and reconciliation.
While not a basic principle, leveraging these systems can reduce errors and improve cash flow visibility. Your outsourced accountant must assist your business in using the capabilities of these ERPs to automate routine financial tasks, including accounts Payable/receivable, inventory management, and financial reporting.
10. CFO-Level Advisory for Strategic Finance
For growing businesses, outsourced CFOs (or VCFOs) offer strategic financial insights beyond day-to-day accounting. They review financial statements, analyse margins, assess cash flow, and help with loan structuring. A strong cash flow forecast is essential to applying accounting principles effectively in real-time.
While not a basic accounting principle, having access to CFO advisory services (on-demand) ensures your outsourced team supports long-term decision-making, not just compliance.
Because in Accounting, ‘Almost Compliant’ Isn’t Good Enough
Outsourced accounting isn’t the problem. Understanding accounting principles is foundational to building a strong CFO financial strategy.
This isn’t just about financial reporting.
That’s why Business Avengers exists to fill the compliance gap with a technically sound and locally trained team. Contact us today!
Want to talk any of this through with a finance leader who has run these functions?
Was this article helpful?
Dilip Kherajani
CPA, Australia and Financial Strategist
20+ years of experience in Finance across multiple industries and geographies, 10+ of them as a CFO.