14 Common Bookkeeping Mistakes Australian SMEs Make and How to Fix Them
Running a small and medium-sized business is no small feat in Australia. You must juggle client calls, inventory, growth strategies, and everyday operations. While you manage all these tasks, bookkeeping may slip from your to-do list for healthy financial records.
These mistakes can cost you time, finances, and compliance with Australian regulations. But don’t worry—every challenge has a solution.
In this blog, we will highlight 15 common bookkeeping mistakes Australian SMEs make and, more importantly, show you how to fix them. Let’s turn those bookkeeping headaches into a streamlined, stress-free process!
14 Bookkeeping Mistakes Australian SMEs Can Avoid
Discover the 14 bookkeeping mistakes Australian SMEs face and how to avoid them for smoother financial management.
2. Neglecting Small Expenses or Payments
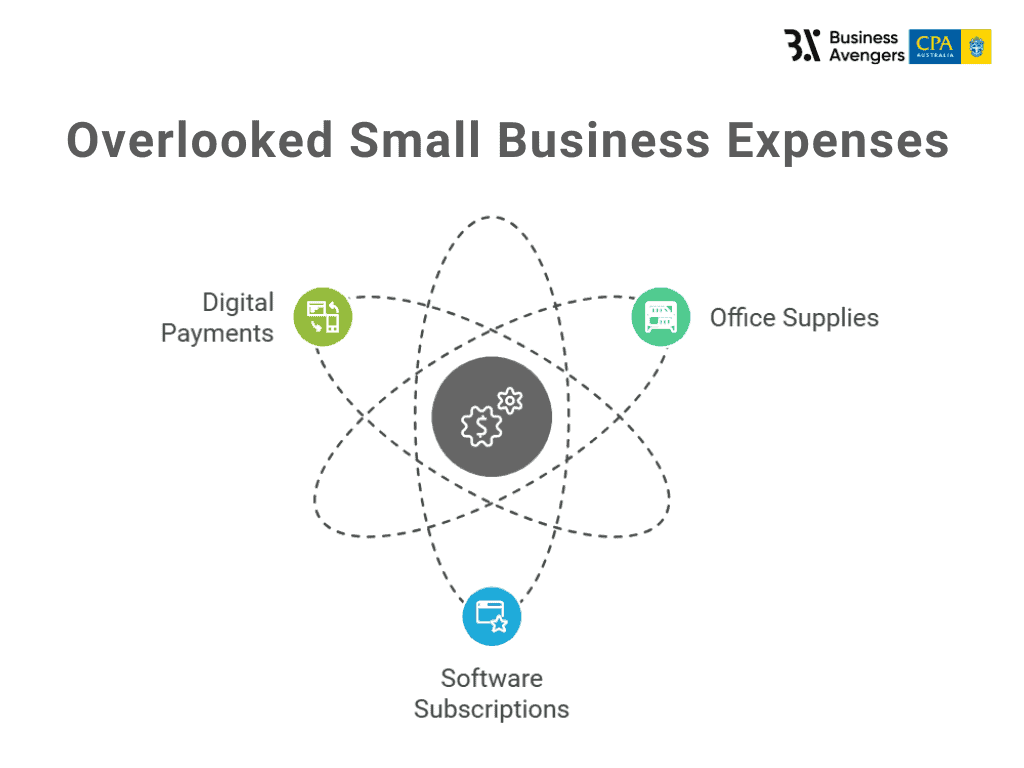
Businesses often neglect small cash flows made on the organisation's behalf, which is a common bookkeeping mistake. It can include anything from office inventory supplies for employees to premium subscriptions to software tools.
However, you must enlist these expenses, including those made by digital modes of payment such as credit cards.
Mistakes can lead to:
How to fix?
Remember, every dollar counts when it comes to maintaining accurate records.
- Use tools like Xero, MYOB, Wave Accounting, and Reckon One to categorise and track expenses systematically, reducing the chance of errors.
- Schedule and update expenses weekly. You can use a business credit card or an Excel spreadsheet to simplify tracking company-related expenditures.
3. Mixing Business and Personal Finances
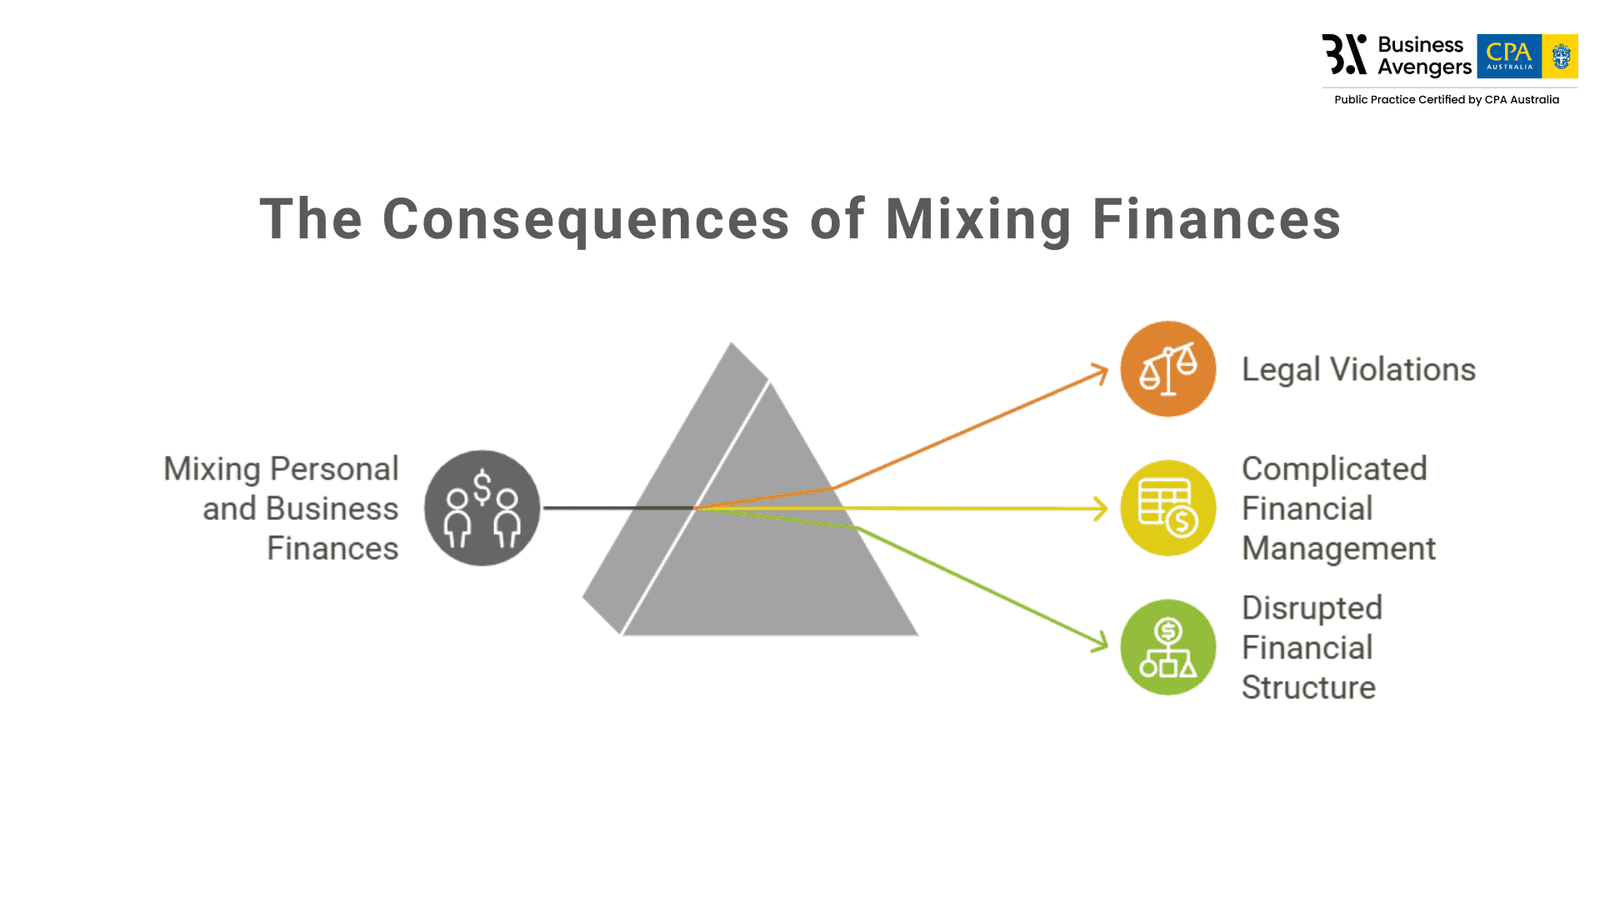
Mixing your personal and professional bank accounts can build a mixed web of tangible assets. You might also end up spending business money on emergency expenses, breaking your business’s financial structure.
Mistakes can lead to:
How to fix?
Pro tip: Having distinct accounts simplifies bookkeeping and portrays your business as a professional entity, improving trust with vendors and clients.
- Mixing funds can lead to potential legal challenges, as separating personal and business assets is critical for compliance.
- Open dedicated bank accounts and credit cards for your business to keep track of income and expenses.
- Using separate accounts makes managing receivables, payables, and bank statement reconciliation easier.
- If you want to transfer funds between accounts, it's best to document it as a personal loan or equity contribution.
4. Haphazardly Managing Receipts and Documentation
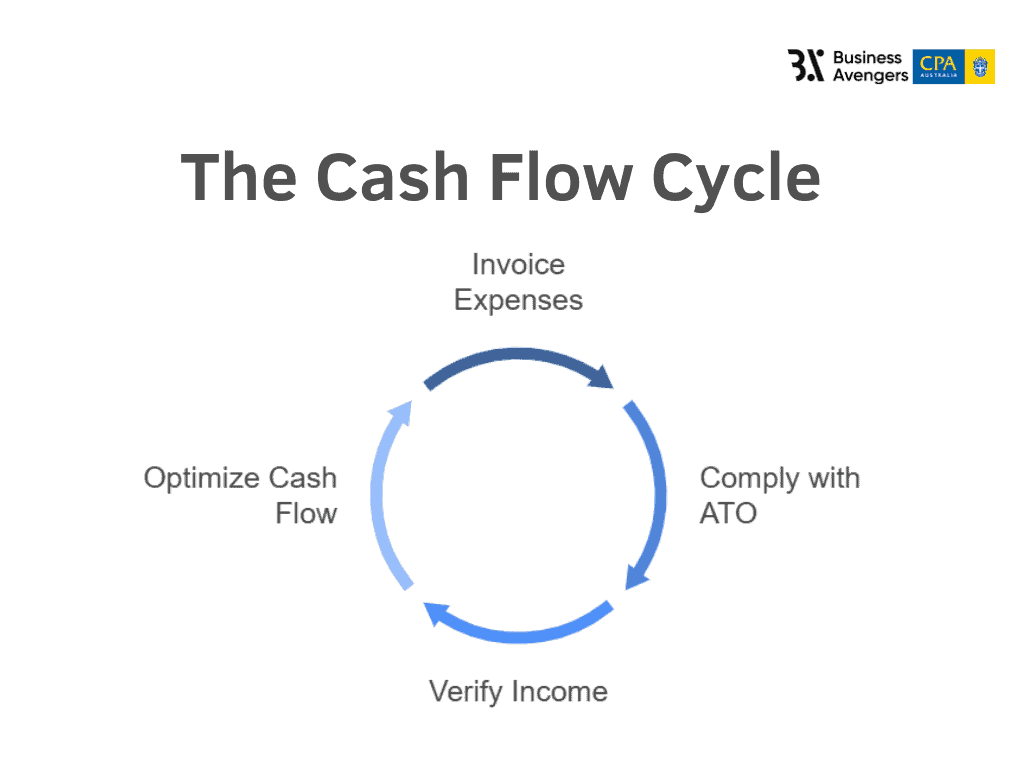
Properly invoicing your expenses is essential to optimise cash flow management, but many Australian SMEs fail to recognise this as a crucial process.
This is where an effective accounts payable and receivable strategy comes in, helping businesses clearly distinguish between inflows and outflows.
Mistakes can lead to:
How to fix?
You can also learn efficient bookkeeping steps to maintain your cash flow management by referring to expert bookkeeping experts in Australia.
- Difficulty in tracking due payments and receivables, resulting in financial drain.
- Poor documentation can harm credibility with vendors and investors.
- Wasting time searching for lost receipts or rectifying errors.
- Create both digital and physical documents of receipts and invoices based on categories such as month, vendor, or expense type. Also, ensure regular backups of digital files to avoid data loss.
- Implement software like Hubdoc, Expensify, or Receipt Bank to digitise your invoices.
- Conduct training sessions to educate employees on the importance of saving receipts and maintaining proper records.
5. Using Accounting Software Without Proper Guidance
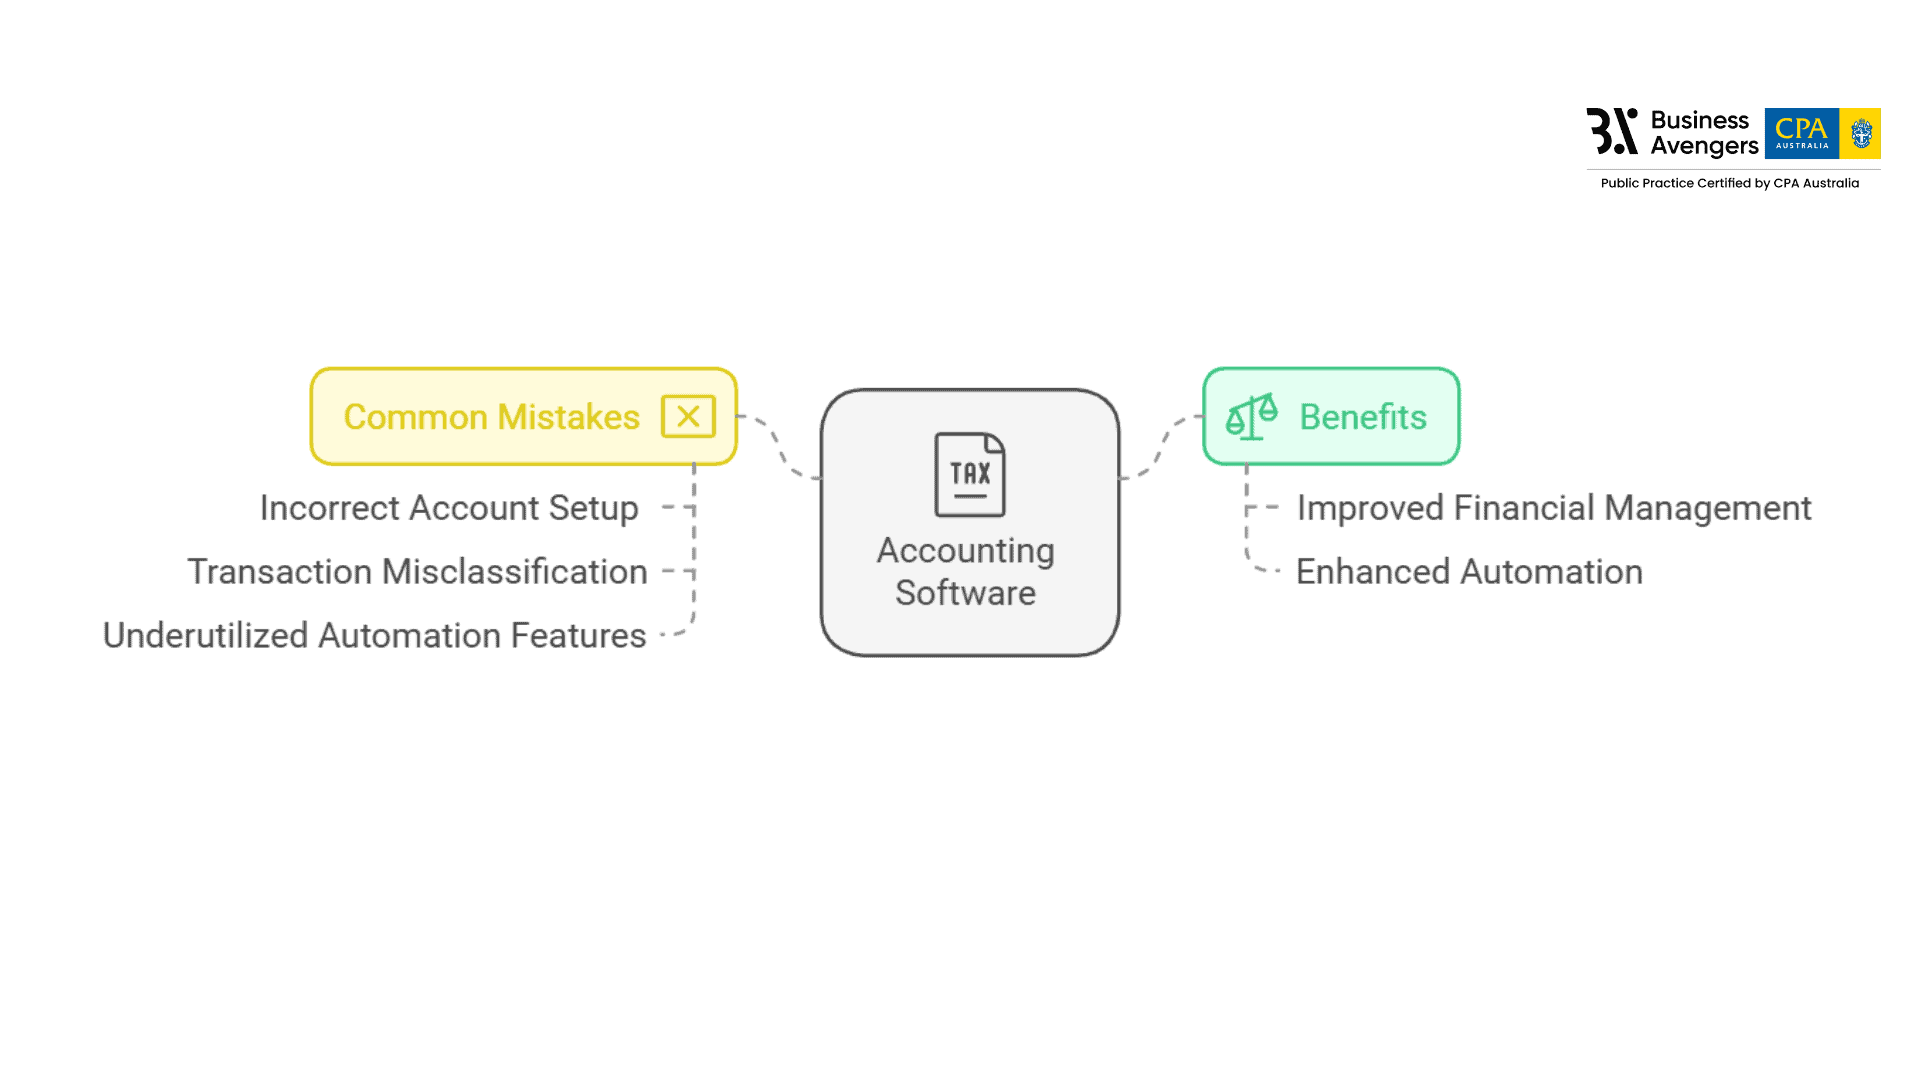
Accounting software like Xero, MYOB, and QuickBooks can boost financial management for Australian SMEs, but improper use often leads to inefficiencies and errors. Without proper guidance, businesses may set up accounts incorrectly, misclassify transactions, or fail to utilise automation features fully.
Mistakes can lead to:
Mistakes can lead to
How to fix?
- Difficulty in tracking due payments and receivables, resulting in financial drain.
- Poor documentation can harm credibility with vendors and investors.
- Engage with an accountant or trusted CFO advisory to ensure the software setup meets your business's needs. You can also have a developer on standby in case digital accessibility becomes a problem.
- Schedule periodic reviews to ensure accounts are categorised correctly, and automated features like invoice reminders function as intended.
- Avoid overloading software with unnecessary integrations initially; stick to core functionalities until your team is confident.
6. Misguiding Cash Transactions
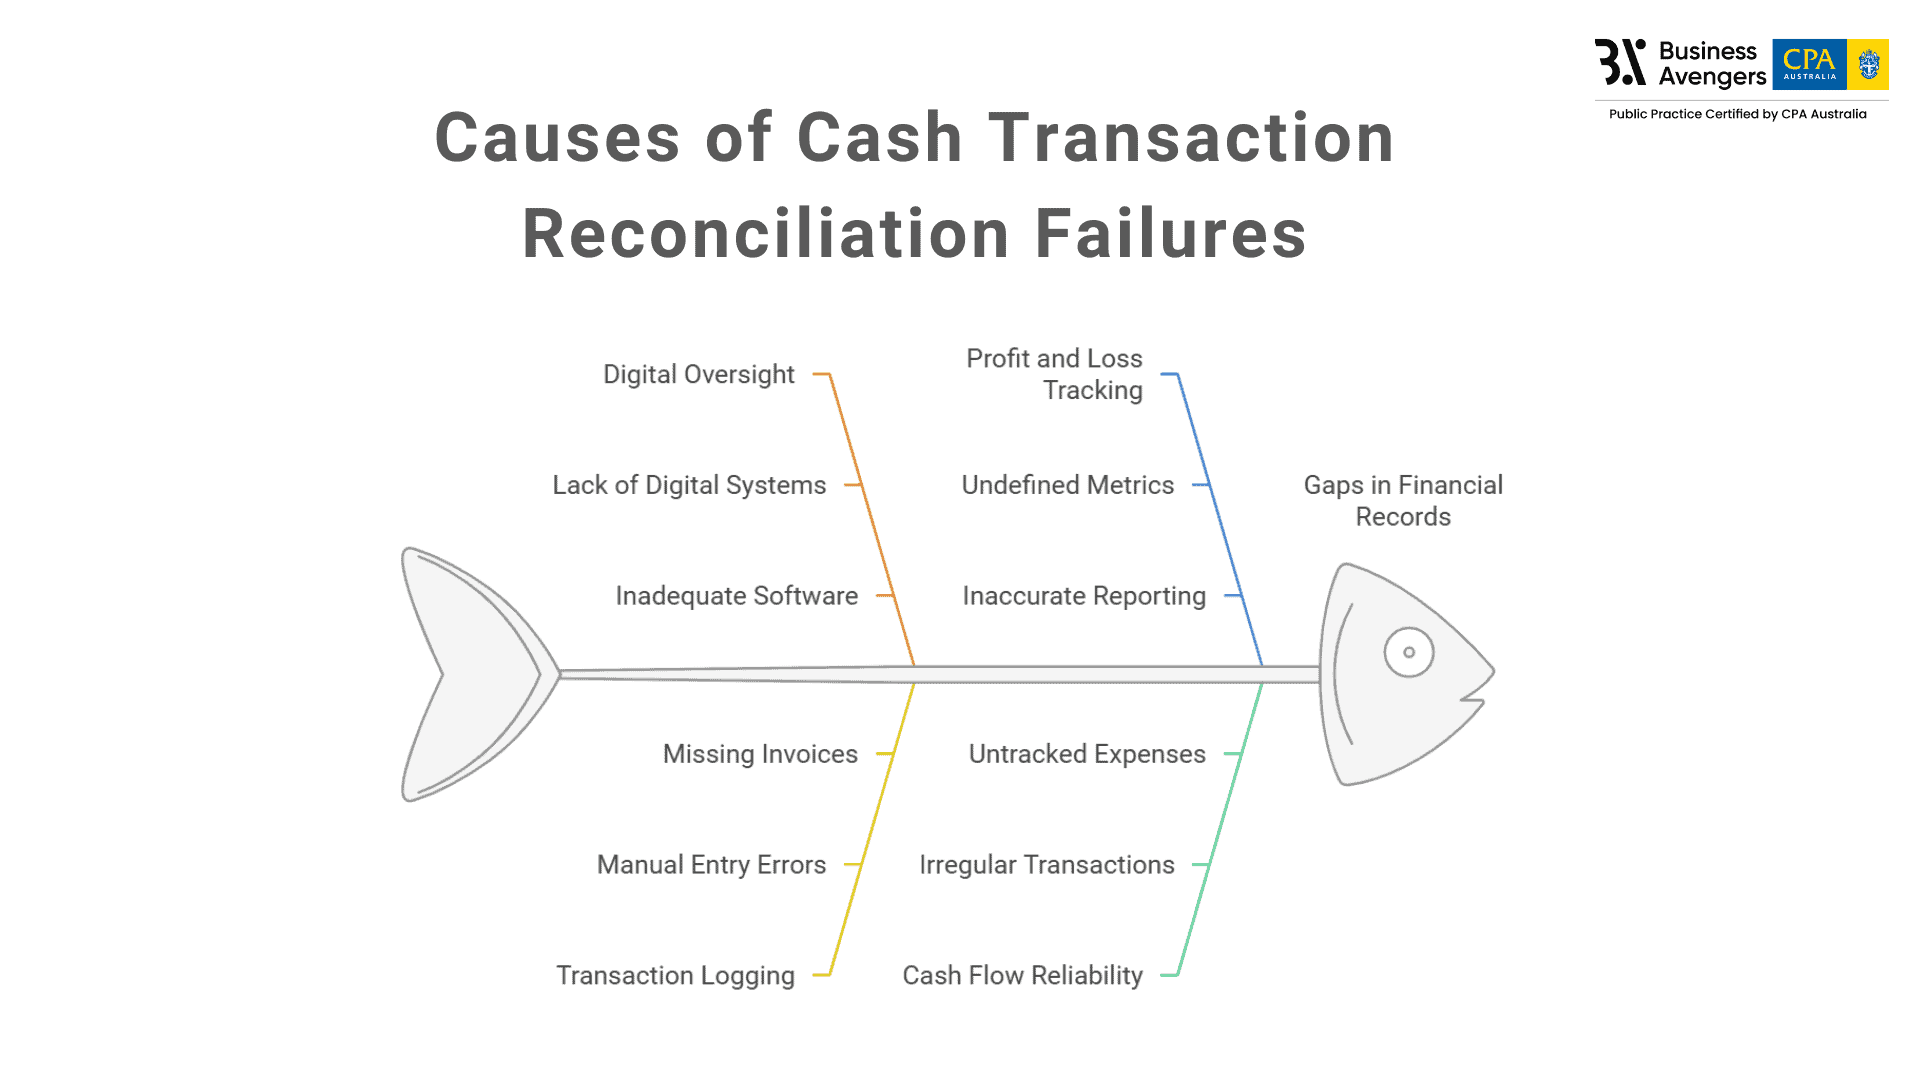
Failing to reconcile cash transactions can often lead to gaps in financial records. Certain transactions might escape digital oversight, making it impossible for you to track profits and losses on overall cash.
For example, retail stores, cafes, and small vendors handle a lot of cash transactions critical for daily operations. Cash flows remain unreliable without proper logging, creating gaps in financial records. You can easily create digital invoice documents to build a record database.
Mistakes can lead to:
How to fix?
Pro tip: Implement cash-handling procedures, such as dual approval for withdrawals, to minimise errors and fraud.
- Inaccurate cash records make it challenging to assess real-time liquidity.
- Unmonitored cash usage can lead to misappropriation or theft.
- Use a dedicated petty cash register or digital tools like Expensify to record every cash transaction, no matter how small.
- Reconcile cash flow regularly to ensure your books match the cash on hand.
- Set clear guidelines for handling cash transactions, such as requiring receipts and expense approvals.
- Whenever possible, encourage digital transactions to improve traceability.
7. Failing to Reconcile Bank Accounts
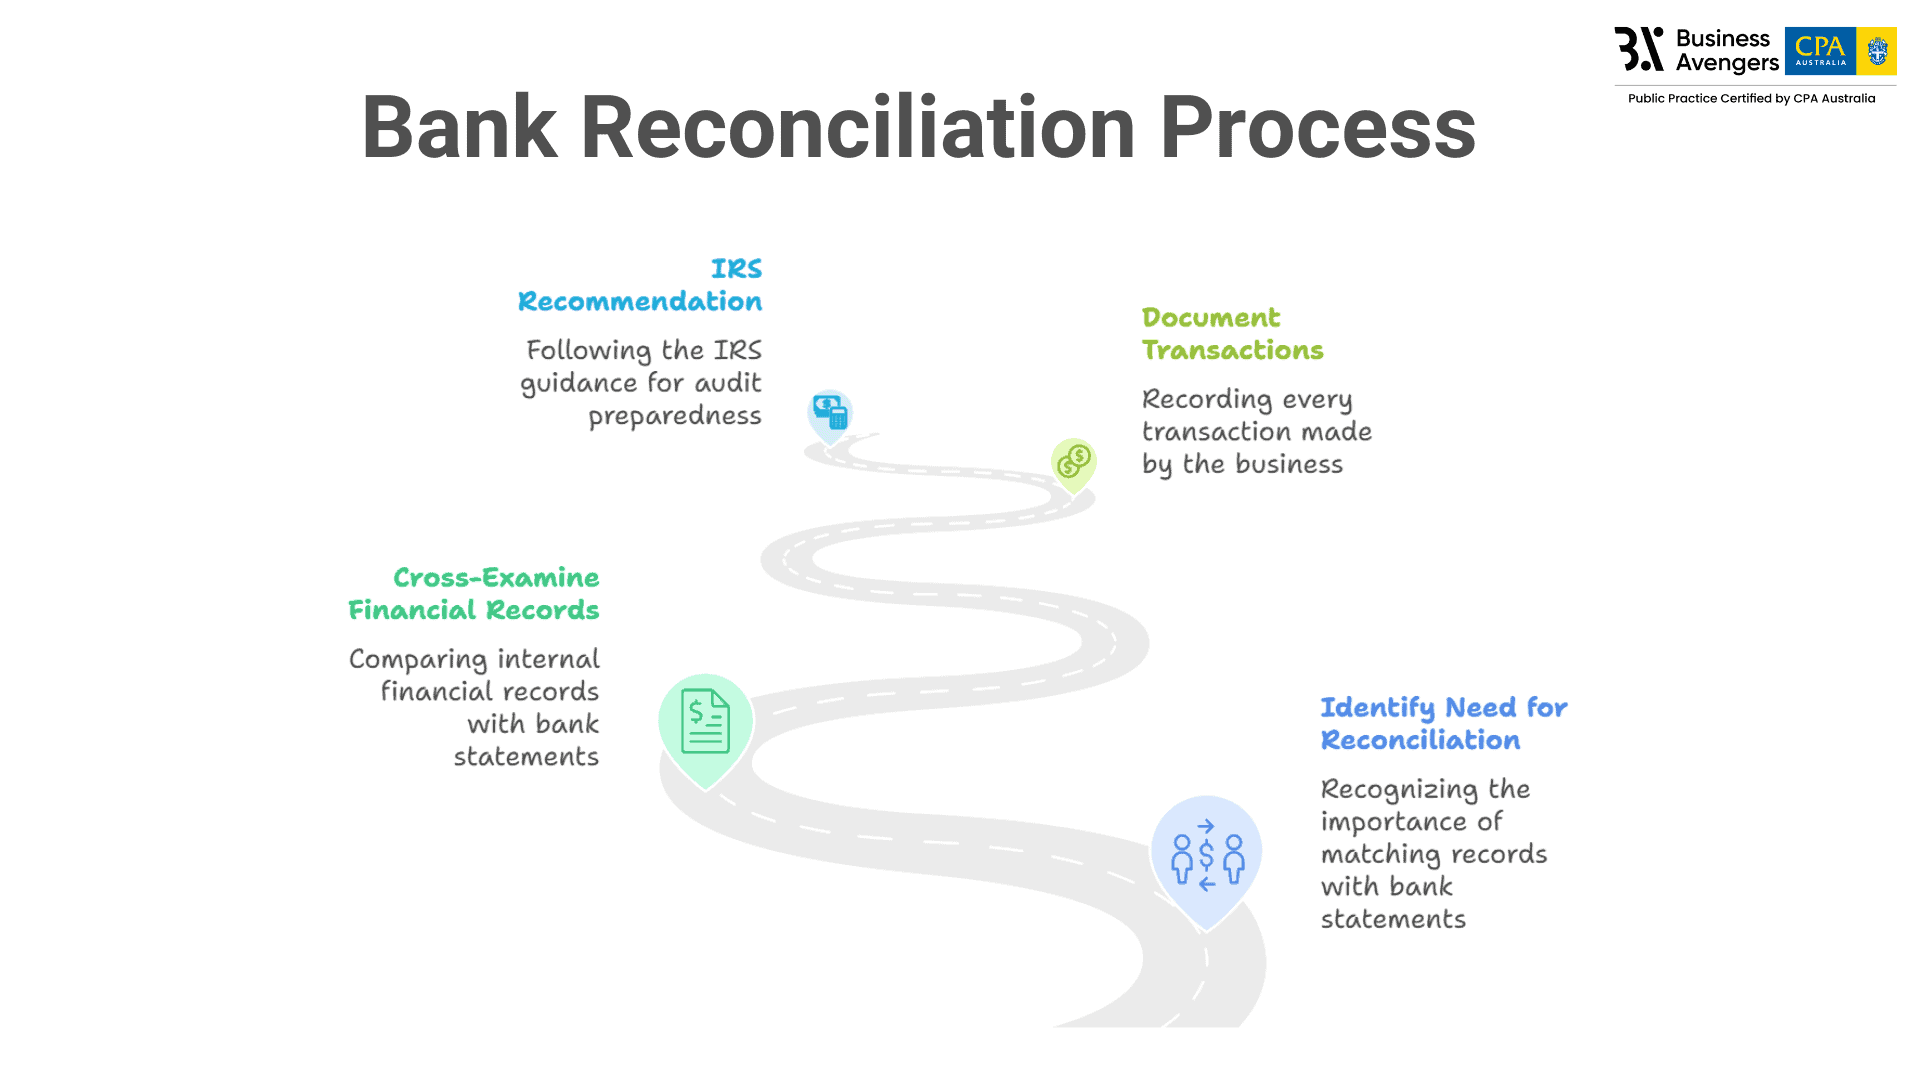
Regularly cross-examining your financial records with bank statements is a common bookkeeping practice often overlooked by business owners.
This practice ensures accuracy and compliance during audits, documenting every transaction in the company's finance records. The cash column in the company financial ledger details the cash on hand, whereas the bank column details the cash on deposit.
Mistakes can lead to:
How to fix?
Schedule a monthly reconciliation routine, regularly verify any discrepancies, and document adjustments between your cash ledger and bank records thoroughly.
Pro tip: Reconcile your accounts weekly instead of monthly to catch unusual errors early and maintain better cash flow visibility. Pair this with maintaining detailed transaction notes for unusual entries, making it easier to resolve issues during audits or financial reviews.
- Missed fraudulent or unauthorised transactions.
- Overdrafts due to overlooked expenses.
8. Delaying Bookkeeping Practices
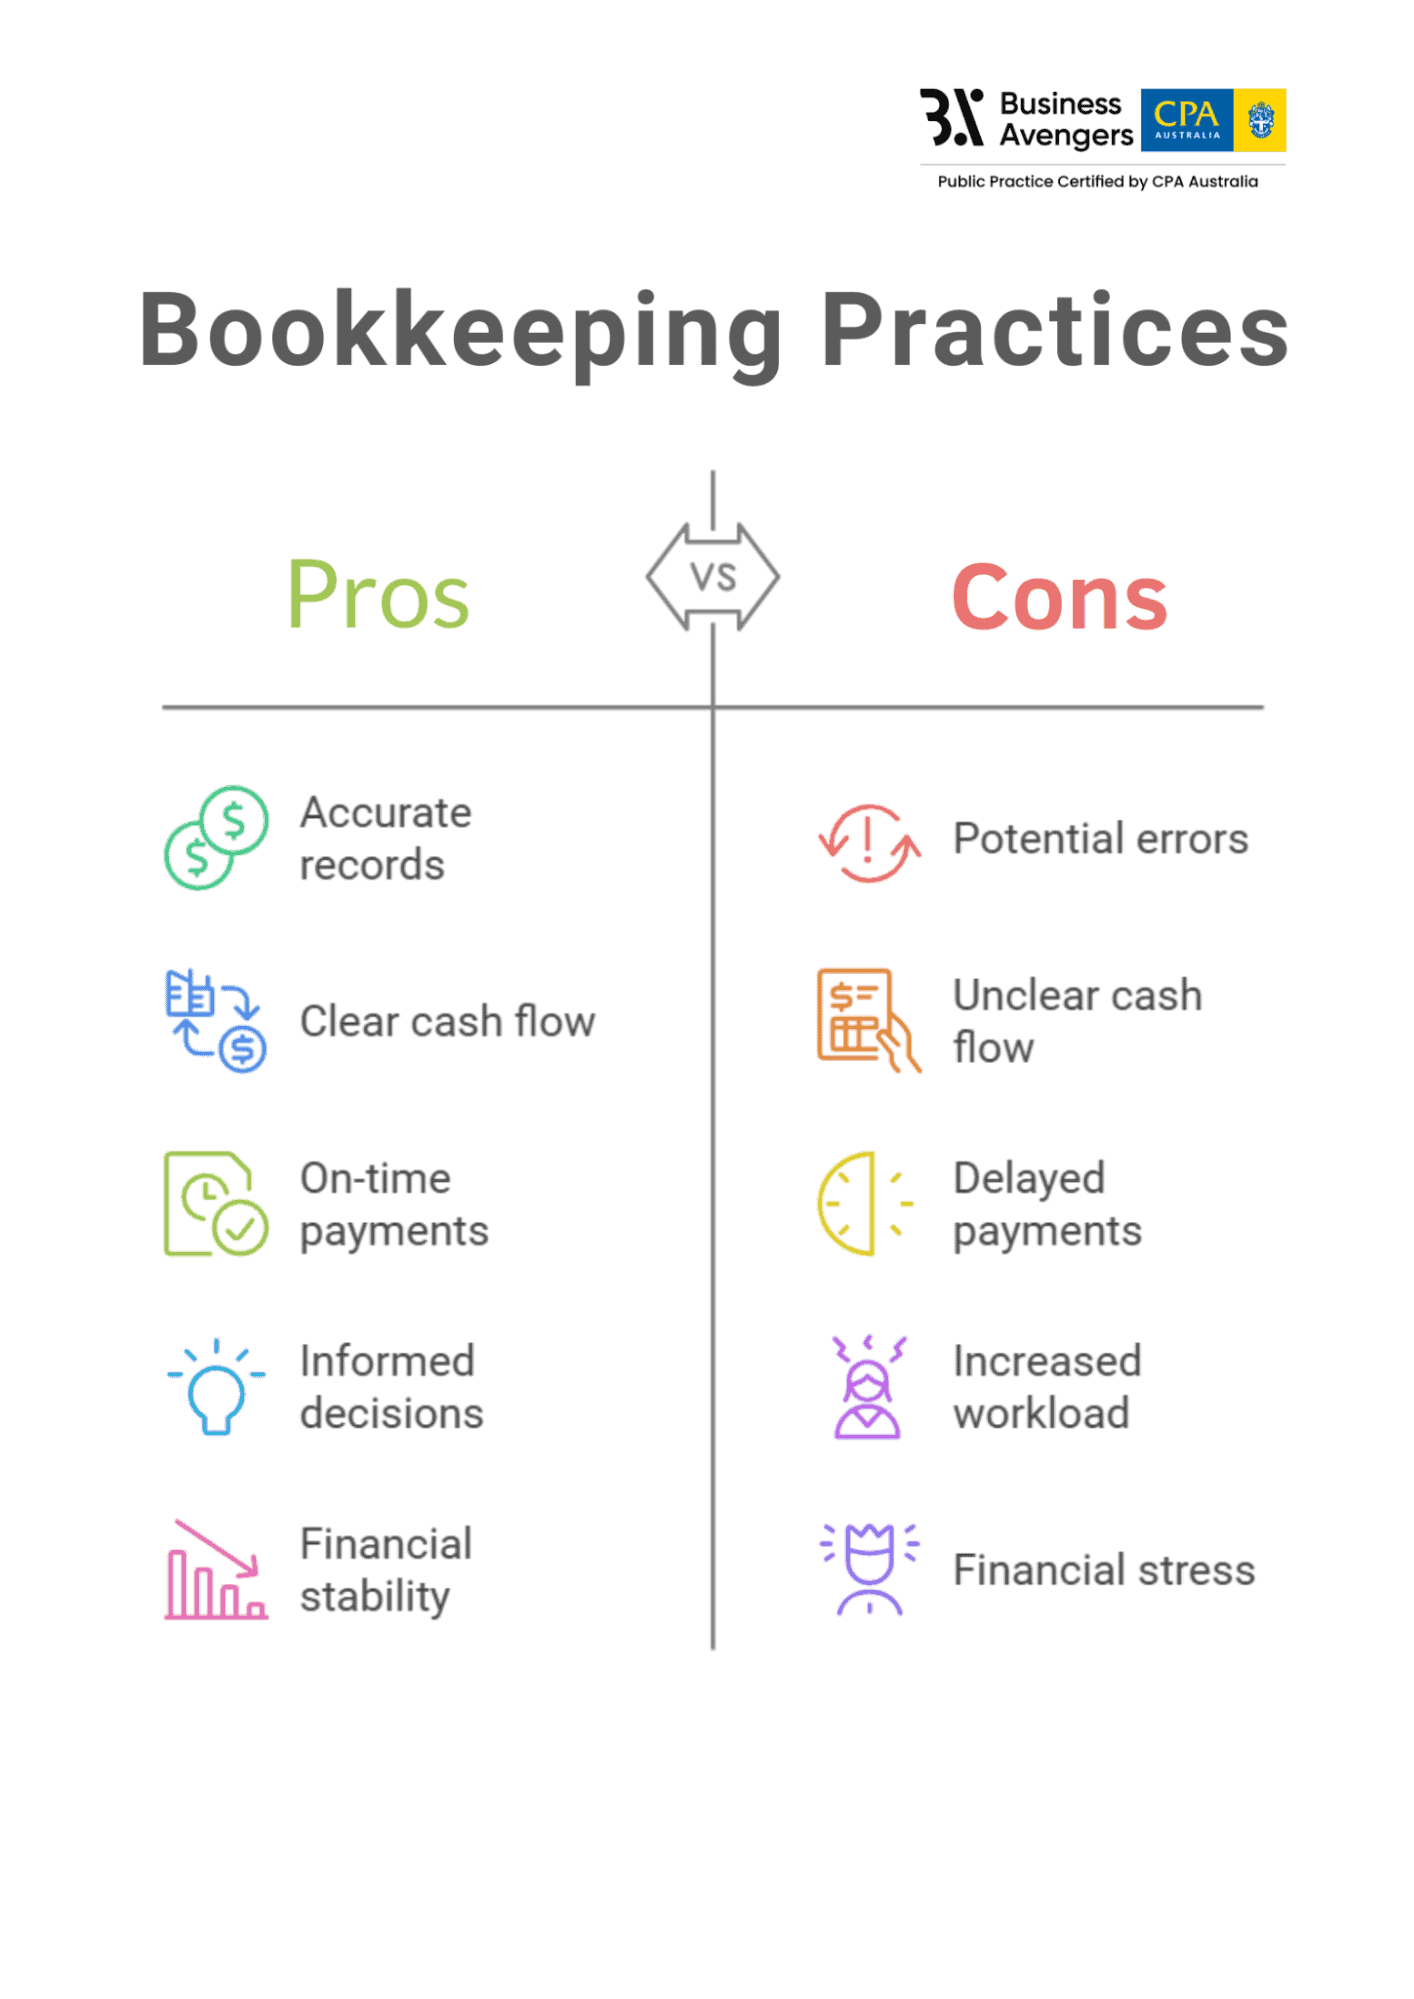
Procrastinating on bookkeeping can snowball into serious financial challenges. When records are not updated regularly, errors pile up, cash flow remains unclear, and critical payments are delayed due to a lack of accurate data.
Timely bookkeeping is not just a task—it's the foundation of informed business operations. It can be done for anything from scenario analysis during economic downshifts to estimating expansion budget forecasting.
Mistakes can lead to:
How to fix?
Pro tip: Hire a part-time bookkeeper if managing records becomes overwhelming.
- Overlooking misguided transactions.
- Inaccurate financial reports that hinder growth planning.
- Allocate a fixed time weekly for bookkeeping tasks.
- Use cloud-based accounting tools like QuickBooks or Xero for real-time updates.
- Use available financial models to project your business's likelihood of success.
9. Overlooking Payroll Compliance
Ignoring these responsibilities can attract penalties and erode employee trust to work with your firm.
Mistakes can lead to:
How to fix?
- Employee dissatisfaction due to delayed or incorrect payments.
- Audits exposing improper record-keeping practices.
- Automate payroll processing with tools like MYOB or Payroller to ensure accuracy.
- Regularly review payroll records for errors and keep detailed documentation.
10. Not Tracking Accounts Receivables
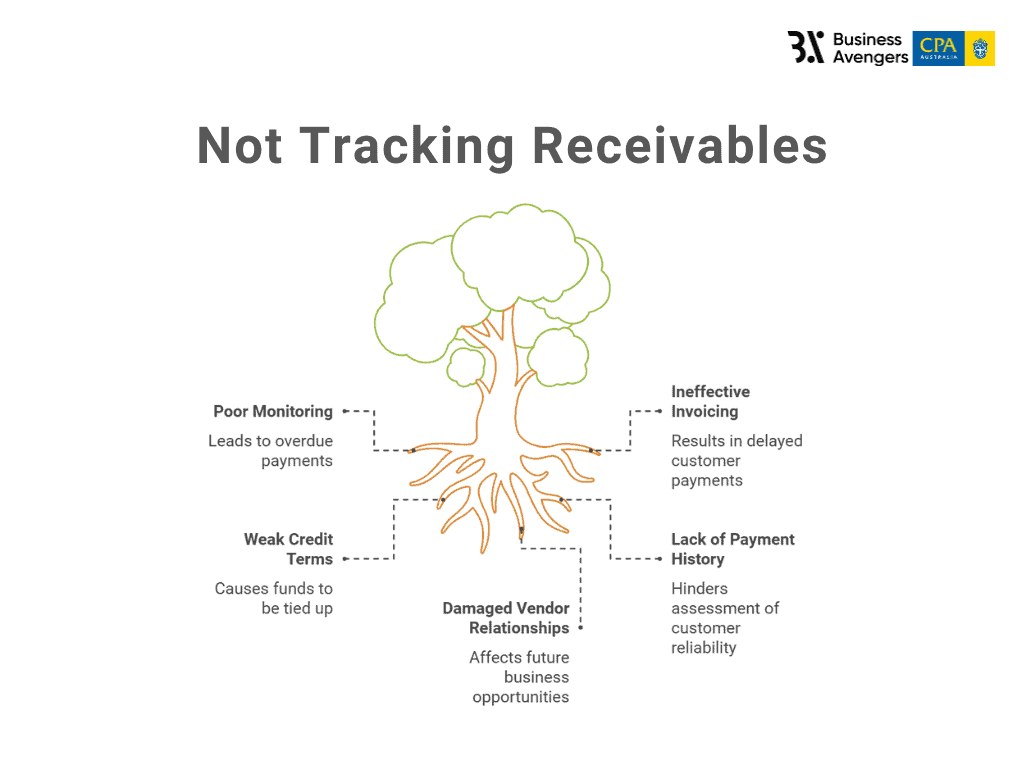
Not tracking your outstanding invoices can cause instability in your cash flow. If your business runs on credit terms and your customers fail to make timely payments, it can lead to cash flow shortages, affecting your business's ability to meet financial obligations.
Mistakes can lead to:
How to fix?
Pro tip: Maintain a detailed record of customer payment histories to identify patterns of late payments. Use this information to adjust credit terms or assess whether to continue offering services to certain customers.
- Difficulty in managing day-to-day financial operations.
- Missed growth opportunities, as funds are tied up in unpaid invoices.
- Damaged relationships with vendors due to delayed payments.
- Regularly monitor your accounts receivable and highlight overdue payments by strengthening their credit terms.
- Use an invoicing system that automatically informs your customers to make on-time payments.
11. Misclassifying Employees
Misclassifying employees as independent contractors or full-time is a common bookkeeping mistake that hinders payroll management. This mistake occurs when businesses fail to understand the legal distinction between the two classifications.
Mistakes can lead to:
How to fix?
Pro tip: Consult with an HR professional or accountant to clearly understand employees based on department, service type, and job entitlements. Alternatively, outsource payroll to Business Avengers for hassle-free operations.
- Employee dissatisfaction due to unpaid benefits or entitlements.
- Legal disputes that damage your business's reputation.
- Use written agreements that outline roles, responsibilities, and classification.
12. Failing to Differentiate Between Cash Flow & Profits
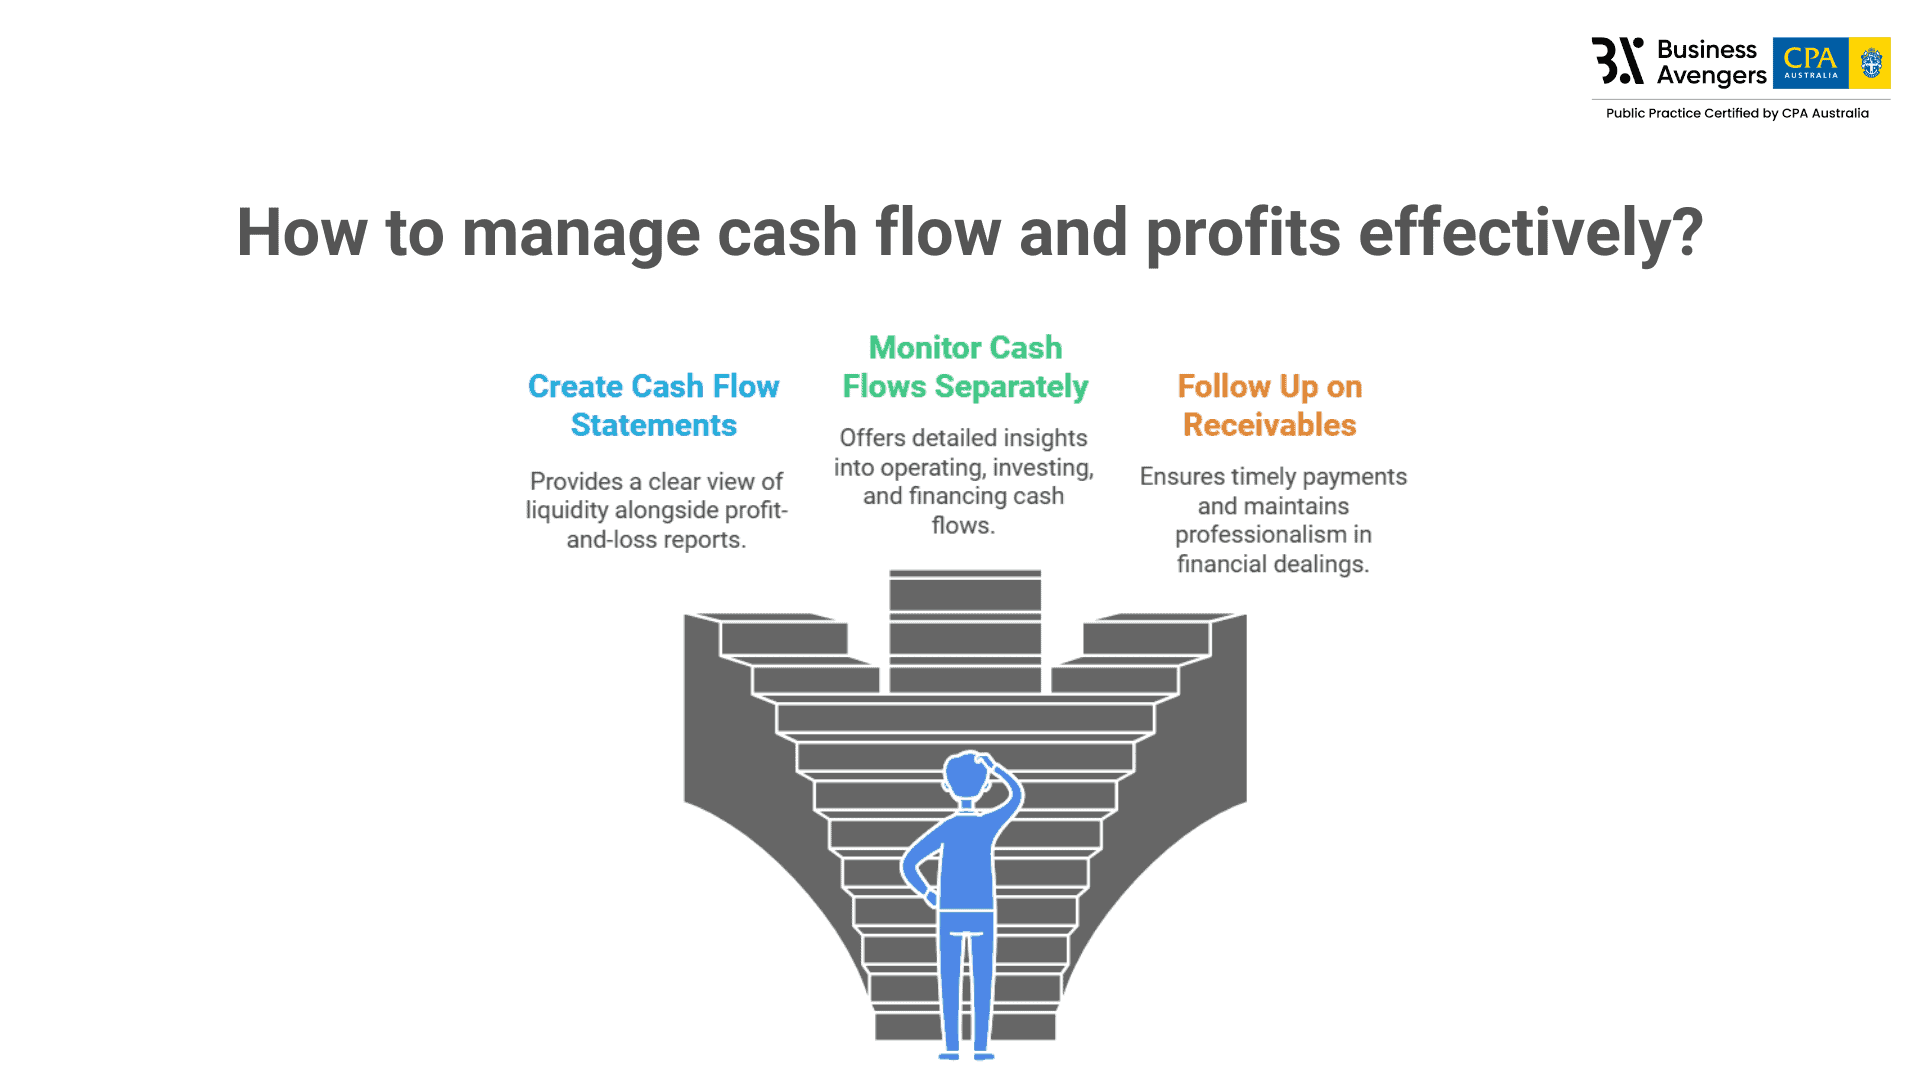
Many businesses confuse cash flow with profits, assuming that high sales automatically translate into financial health. Well, this is a common bookkeeping mistake where businesses might struggle with cash flow if revenues are tied up in receivables or delayed payments.
While profits show long-term viability and overall earnings after expenses, cash flow represents the money needed to cover daily expenses.
Mistakes can lead to:
How to fix?
Pro tip: Use tools like Xero or QuickBooks to generate real-time cash flow reports and make informed decisions.
- Inability to meet short-term obligations like rent, payroll, or supplier payments.
- Overestimating financial stability leads to poor surplus funds.
- Challenges in securing loans or investments due to inconsistent cash flow.
- Create a cash flow statement alongside profit-and-loss reports to track liquidity.
- Monitor operating, investing, and financing cash flows separately for a clearer picture.
- Monitor payment cycles and actively follow up on outstanding receivables to maintain professionalism in payments.
13. Writing Off Significant Purchases as Immediate Expenses
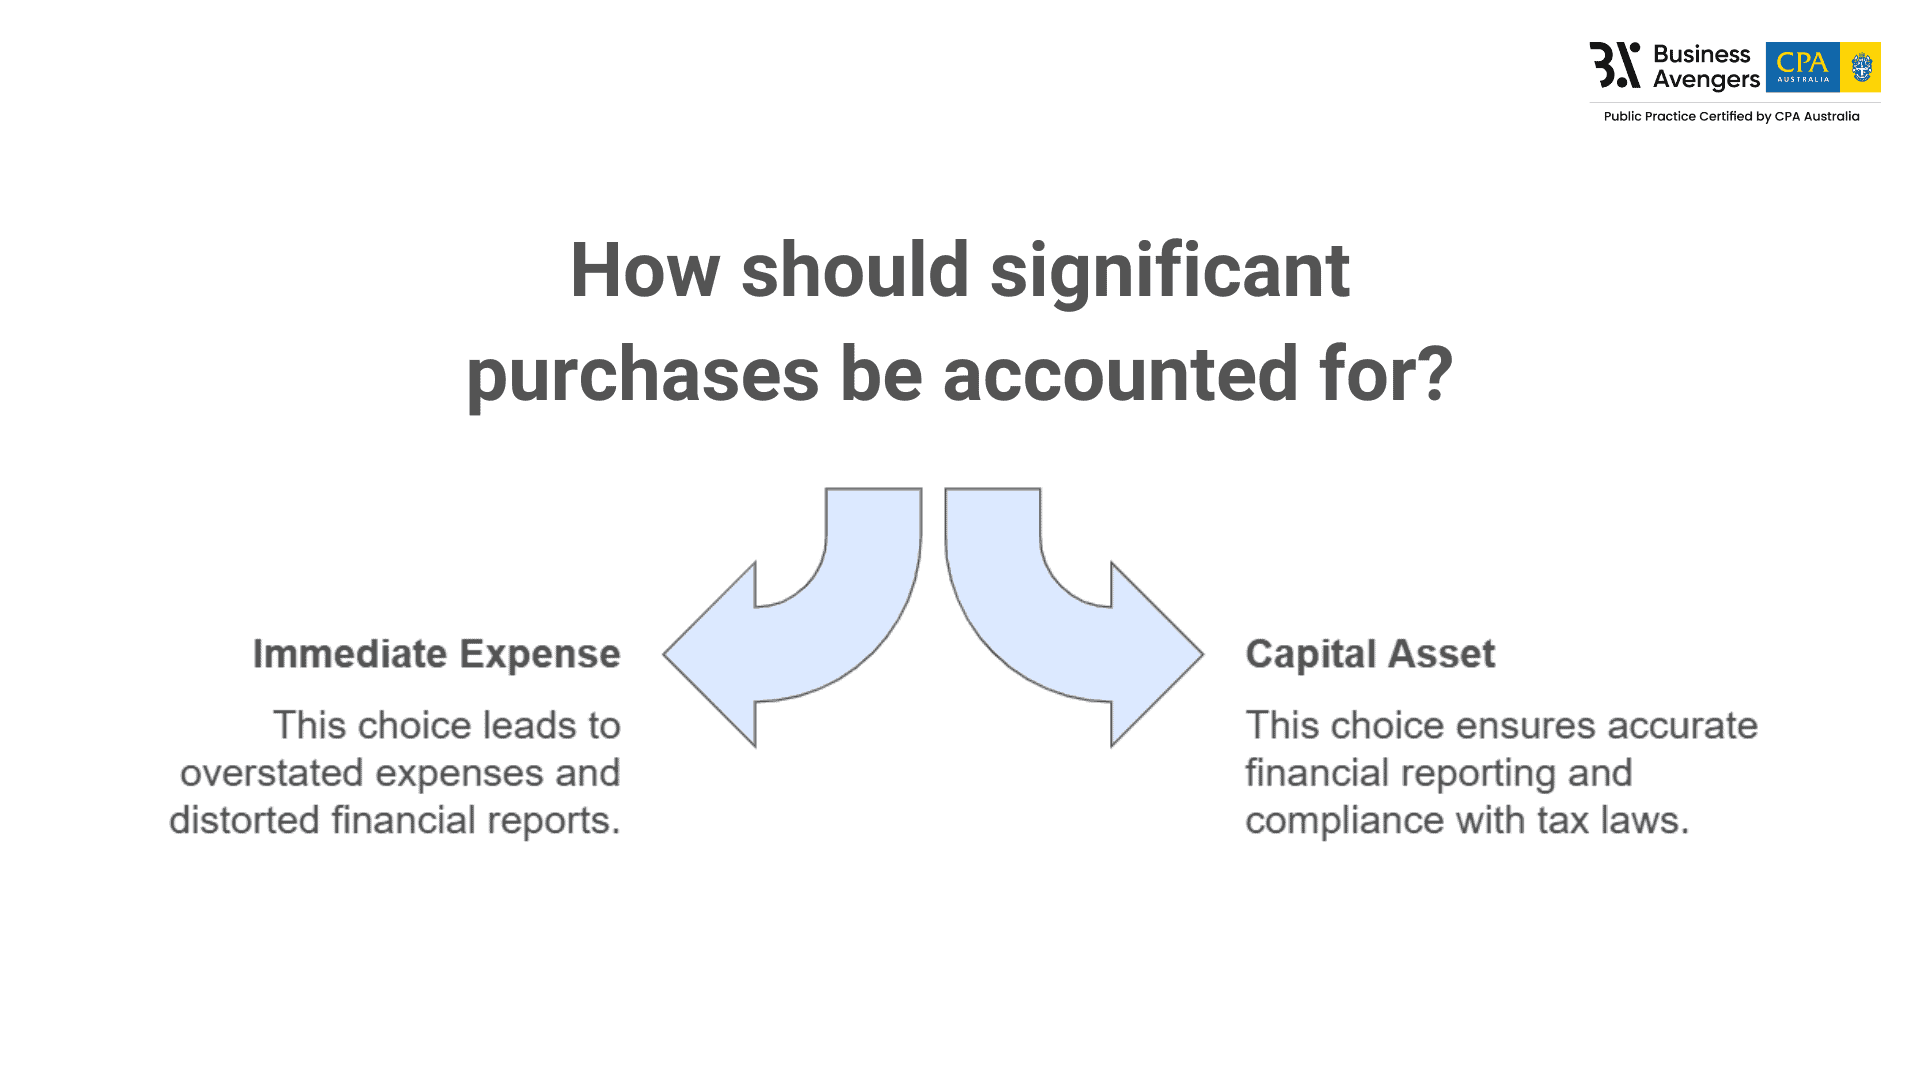
Expensing large purchases immediately rather than depreciating them over time is a common bookkeeping mistake. Major investments such as vehicles, equipment, or office furniture are company assets and must be allocated based on their durability.
Writing such expenses as immediate expenses can reduce net income in the short term, leading to inaccuracies in profit reporting.
Mistakes can lead to:
How to fix?
Always consult with your accountant to determine which purchases qualify as capital assets and establish appropriate depreciation schedules.
- Distorted financial reports, affecting investor trust and decision-making.
- Identify which purchases qualify as capital expenses (e.g., machinery, office equipment).
- Allocate such purchases to an asset account and calculate depreciation annually.
14. Lacking Proper Communication With Your Bookkeeper
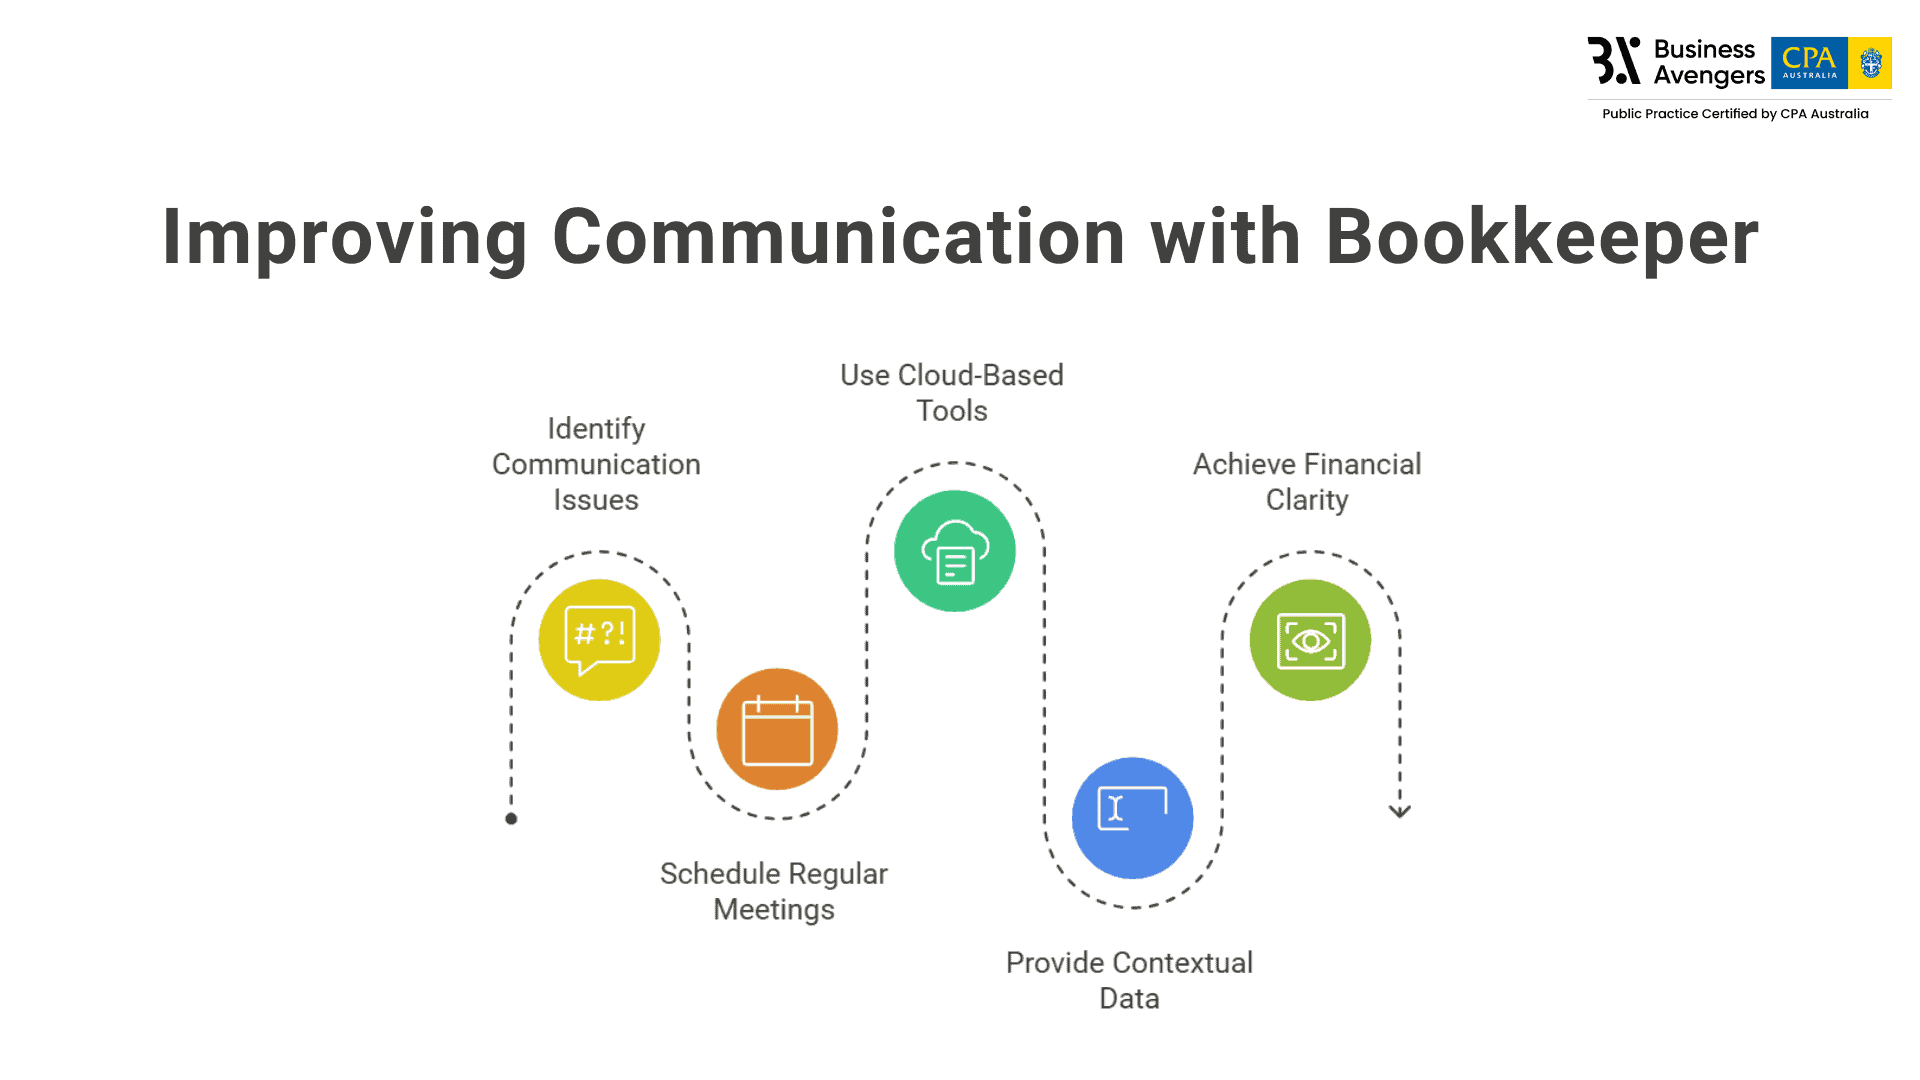
Outsourcing the bookkeeping department to a professional is a wise choice for businesses facing cash flow problems. However, proper communication with your bookkeeper keeps you ahead of misunderstandings, errors, and missed opportunities boosting finances.
Mistakes can lead to:
How to fix?
Pro tip: Label receipts by category or provide details about one-off expenses to help your bookkeeper accurately record them.
- Misaligned expectations, resulting in incomplete or incorrect records.
- Delayed financial reports, hindering strategic planning.
- Schedule weekly or biweekly meetings to review progress, share updates, and discuss upcoming tasks.
- Use cloud-based tools like Google Drive, Dropbox, or accounting software with shared access to upload invoices, receipts, and bank statements.
- When submitting data, give context where necessary. Tools like Xero, QuickBooks, or MYOB provide shared access, comments, and updates to keep everything transparent.
Mastering Bookkeeping: Avoiding Mistakes for Better Accounts Management
Financial stability begins with effective cash management, which hinges on accurate and informed bookkeeping practices. Aligning your payables and receivables ensures smooth financial operations without requiring additional funding.
This blog has highlighted common bookkeeping mistakes and practical solutions to overcome them, empowering you to maintain accurate records, streamline operations, and build a stronger financial foundation for your business's growth.
Want to talk any of this through with a finance leader who has run these functions?
Was this article helpful?
Dilip Kherajani
CPA, Australia and Financial Strategist
20+ years of experience in Finance across multiple industries and geographies, 10+ of them as a CFO.